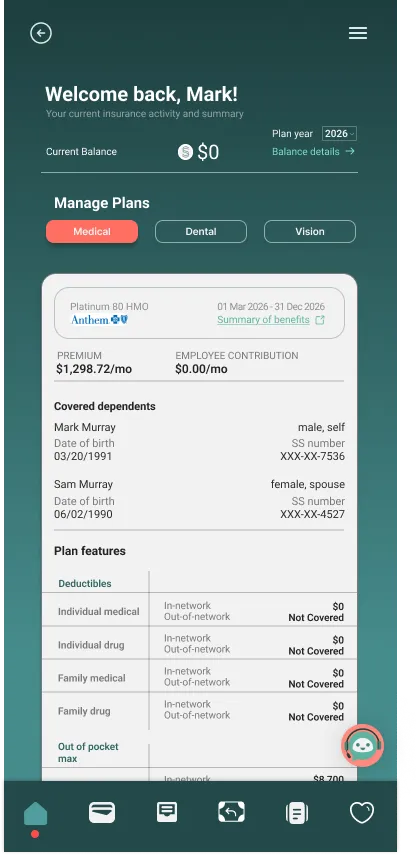
Stop Overpaying for Group Health Insurance. Meet Direct-Pay ICHRA.
SimplyHRA is the Direct-Pay ICHRA platform that pays employee health insurance premiums directly through pre-funded virtual Visa cards. Lock in a fixed monthly budget, cut renewal volatility by 20-35%, and eliminate out-of-pocket reimbursement waits across all 50 states.
Flat $29 per enrolled employee/month ($0 setup, $0 base fee) -- All 50 States -- 1:1 Licensed Benefits Specialists -- 60-Day Money-Back Guarantee.

Why reimbursement-only HRAs feel broken -- and how Direct-Pay ICHRA fixes them.
SimplyHRA makes it easier to offer personalized healthcare to your employees. Set your budget. Employees pick their plans. We handle the rest.

Pre-funded virtual Visa card (Feature #1)
Every enrolled employee gets a pre-funded virtual Visa card loaded with your monthly allowance. It pays the insurance carrier directly -- zero out-of-pocket premium float and zero 4-week reimbursement waits.

Employee choice
Each employee picks the plan that fits their doctors, prescriptions, and family. Assign different plans to employees in different states. No more one-network-fits-all.

Fixed monthly budget (20-35% savings)
Set a fixed monthly allowance per employee class. A 15-person team switching from a $680 PEPM group renewal to a $500 ICHRA allowance saves $27,180/year with 100% pre-tax deductions.

Compliance
We generate plan documents, ICHRA notices, tax documents, and ACA-ready reports so you stay compliant without becoming a benefits expert.

Benefits specialist
Every employee gets access to a licensed, local benefits specialist who helps them compare plans and enroll at no extra cost. No more shopping on Healthcare.gov alone.

Plan flexibility
Structure your HRA to reimburse eligible premiums and medical expenses. To preserve HSA eligibility, use a premium-only, limited-purpose, or post-deductible design. Any employer HSA contributions are made separately from the HRA.
Your benefits under control
A self-serve platform for employers and employees -- with real human support whenever you or your colleagues need it.

Set Your Budget & Fund Cards In Minutes
Choose how much to reimburse per employee class (full-time, part-time, by location). No minimums, no maximums. Change it annually as your budget grows.

Employees Pick Plans That Fit Their Lives
A licensed benefits specialist helps each employee compare ACA marketplace and private plans that can cover their doctors, prescriptions, and family. Included at no extra cost.

Virtual Cards Handle Payments
Each employee gets a pre-funded virtual card that pays their insurance premium directly. Employees then upload proof of payment to SimplyHRA for compliance and approval.

Ongoing Personalized Support via Email, Call, or Text.
Our team and AI assistant help with eligibility questions, plan changes, regulations, and compliance via email, phone, or chat so neither you nor your employees are ever stuck.
Simple and transparent pricing
No setup fees. No onboarding fees. No platform fees. No switching fees. One price. You only pay for employees who are enrolled. If an employee doesn't participate, there's no charge.
No hidden fees.
$29/mo
per employee
Set up your ICHRA plan in minutes.
Licensed benefits specialist for every employee, included.
Audit-ready compliance reports and plan documents.
Employee reimbursement requests and approvals handled in one place.
Employer-to-employee reimbursement payments, automated.
Virtual card for direct premium payments.
Automatic expense classification and partial reimbursements.
Priority + onboarding customer support
Loved by employees and business owners!
SimplyHRA helps businesses offer the best benefits experience possible to their W2 employees.
Huseyin S., Owner -- Multi-State SMB (14 Employees, TX & CA)
Huseyin S., Small Business Owner
Rob Bircher, Co-Founder -- Kinside (YC S18, Distributed Startup)
Rob Bircher, Co-Founder - Kinside (S18)
Sinem Topcu, HR Manager -- Kidsy (18 Employees, Chicago IL)
Sinem Topcu, HR Manager - Kidsy
"I was nervous about losing my group plan but SimplyHRA's benefits specialist found me one within a week that allows me to keep my doctor while paying less out of pocket. The virtual card pays my premium on auto-pay."
Basmah M., Lead Product Designer -- Enrolled Employee (California)
ICHRA FAQs
Common questions from employers and employees about how ICHRA works.
How does the virtual card work?
SimplyHRA supports both Direct-Pay Virtual Cards and traditional reimbursements: (1) For monthly insurance premiums, your employer pre-funds a virtual Visa card each month so your carrier bill is paid directly on autopay with $0 out-of-pocket wait, and you upload your carrier invoice for IRS Section 105 substantiation. (2) If your plan also covers out-of-pocket medical expenses (copays, prescriptions, deductibles), you can submit receipts for fast tax-free ACH reimbursement.
What if an employee doesn't enroll in health coverage?
Employees must have qualifying individual health coverage (such as a plan from the ACA marketplace or a private insurer) to receive reimbursements. If they don’t enroll in a plan, they won’t be eligible for ICHRA funds. However, your business only reimburses actual expenses, so you never pay for unused benefits.
Can employees who enroll in our ICHRA still take Marketplace premium tax credits?
Generally no. If an employee accepts an ICHRA that’s deemed “affordable,” they are ineligible for premium tax credits for those covered months. If the ICHRA is unaffordable, the employee may decline it and pursue credits on the Marketplace. Affordability compares the employee’s required contribution for the lowest-cost silver plan (self-only), net of the employer allowance, to the IRS affordability threshold.
Are business owners eligible to participate?
C-Corp owners on W-2 payroll (and LLCs taxed as C-Corps) are eligible for 100% tax-free ICHRA participation. Under IRC Section 1372, >2% S-Corp shareholders and LLC partners deduct premiums via W-2 Box 1 / Form 1040 Schedule 1 while offering tax-free ICHRA benefits to their non-owner W-2 staff.
When can employees pick plans -- can they start mid-month?
Individual health coverage generally starts on the 1st of a month (Marketplace rules). Your ICHRA can start any day but can not cover previous month costs. New hires and qualifying life events trigger special enrollment windows.
Can employees buy any plan they see on the public Marketplace?
Yes -- eligible employees can shop and enroll in individual major medical plans on- or off-exchange, subject to enrollment windows. For tax-free reimbursement, the plan must meet Minimum Essential Coverage (MEC).
Does SimplyHRA help employees choose qualified medical, dental, or vision coverage?
Yes. Every employee gets a free, one-on-one call with a licensed benefits specialist who reviews your family size, doctors, prescriptions, and budget to recommend the best plan options. We’re authorized in all 50 states.
How long does onboarding take?
Most employers are fully set up in 2–3 weeks. Employees receive their virtual cards within 3–5 business days after submitting enrollment documents. If you have an urgent hire, we can expedite.
Is the HRA contribution pre-tax or post-tax?
For employers, eligible HRA reimbursements are generally deductible business expenses. For employees, properly substantiated reimbursements are generally tax-free. Any unreimbursed premium amount is normally paid after tax, unless the employer offers a Section 125 cafeteria plan and the employee has eligible off-Exchange individual coverage. Marketplace premiums cannot be paid through Section 125 salary reduction.
Still have questions?
Can’t find the answer you’re looking for? Contact us! We're here to help.
HRA blog, glossary, and more
Resources for employers and employees to learn more about HRA benefits.

How to Offer Health Benefits for a 10-Person Company in 2027: Cost Models & Payroll Setup
Compare the 3 legal ways to offer health benefits for a 10-person company in 2027: Small Group, Taxable Stipend, and SimplyHRA Direct-Pay ICHRA.
Read post
2027 QSEHRA Contribution Limits, Pro-Ration Math & ICHRA Upgrade Thresholds
Review the 2027 QSEHRA contribution limits ($6,450 self-only / $13,100 family), mid-year hire pro-ration math, W-2 Box 12 Code FF rules, and ICHRA.
Read post
Group Health Insurance
Understand group health insurance basics and options for small businesses, HR managers, and employees to optimize benefits and costs.
Read post
GCHRA (Group Coverage HRA)
Learn how GCHRA (Group Coverage HRA) works for small businesses, offering flexible health benefits while simplifying employer and employee responsibilities.
Read post
Ready to Cut Your Benefits Costs and Give Employees Better Coverage?
Schedule a free 15-minute consultation. We’ll walk you through a demo, pricing, the virtual card, and exactly how setup works. No commitment required.
Happier employees with plans they love.
Easy to set up.
Tax-free employer contributions.